Built for practitioners
I built the resource I wished existed when I started managing currency exposure across multiple horizons
I spent years watching portfolio managers struggle with hedge ratio decisions that
textbooks oversimplified and vendors overcomplicated. So I assembled a team of
quantitative researchers, former institutional traders, and risk engineers to build
something different: frameworks that respect the real constraints of multiperiod
currency hedging. No black boxes. No generic rules of thumb. Just rigorous models you
can adapt to your own data and governance.
Multiperiod hedge optimization
Governance-ready frameworks
Built by practitioners
Adaptable to your data
Why we built this platform
Currency hedging is not a one-size-fits-all decision. Yet most guidance treats it that way. We set out to change that.
The gap we saw
The gap we saw
Existing resources fell into two camps: oversimplified academic models that
ignored transaction costs and rebalancing frictions, or vendor black boxes
that offered no transparency into how hedge ratios were derived.
Practitioners needed something in between — rigorous enough to justify to
boards, flexible enough to adapt to real portfolios. I watched colleagues
waste quarters calibrating models that were never designed for their
constraints.
What we built instead
What we built instead
We developed open-architecture frameworks that separate the optimization
engine from the data layer. You bring your covariance assumptions, your cost
functions, your governance boundaries. Our models generate hedge ratio
trajectories and rebalancing schedules that you can inspect, stress-test,
and defend. Every parameter has an economic interpretation. Every output can
be replicated.
Who it is for
Who it is for
This platform serves institutional allocators, corporate treasury teams, and quantitative researchers who manage currency exposure across multiple investment horizons. Whether you rebalance monthly or annually, whether you face tight tracking error budgets or loose ones, the frameworks adapt. We assume you already understand forwards, options, and basis risk. We help you decide how much to use and when to adjust.
How we work
How we work
Our process follows a three-step consultation. First, we map your current
hedging policy against your actual portfolio dynamics. Second, we calibrate
our multiperiod models to your cost structure and risk preferences. Third,
we deliver implementable hedge ratio schedules with full documentation of
assumptions and sensitivity analyses. You retain full control of execution
and data.
Where we are headed
Where we are headed
We continue refining our models for emerging market currency pairs,
cross-asset hedging, and ESG-constrained portfolios. The research agenda is
public and practitioner-driven. We publish working papers, run simulation
challenges, and incorporate feedback directly into framework updates. This
is not a finished product. It is a living system that evolves with the
markets it models.
The people behind the frameworks
Dr. Elena Vasquez-Chen
Founder and Lead Quantitative Researcher
Former head of currency research at a European asset manager, Elena spent twelve years building hedge ratio models for pension funds and sovereign wealth funds before founding this platform.
James Whitfield-Okonkwo
Head of Model Implementation
James translates theoretical frameworks into production-ready code. He previously led the quant engineering team at a London-based currency overlay manager.
Sarah Lindqvist-Berg
Risk Governance Advisor
Sarah advises on how to present hedge ratio decisions to investment committees and regulators. She joined from a Nordic central bank reserve management unit.
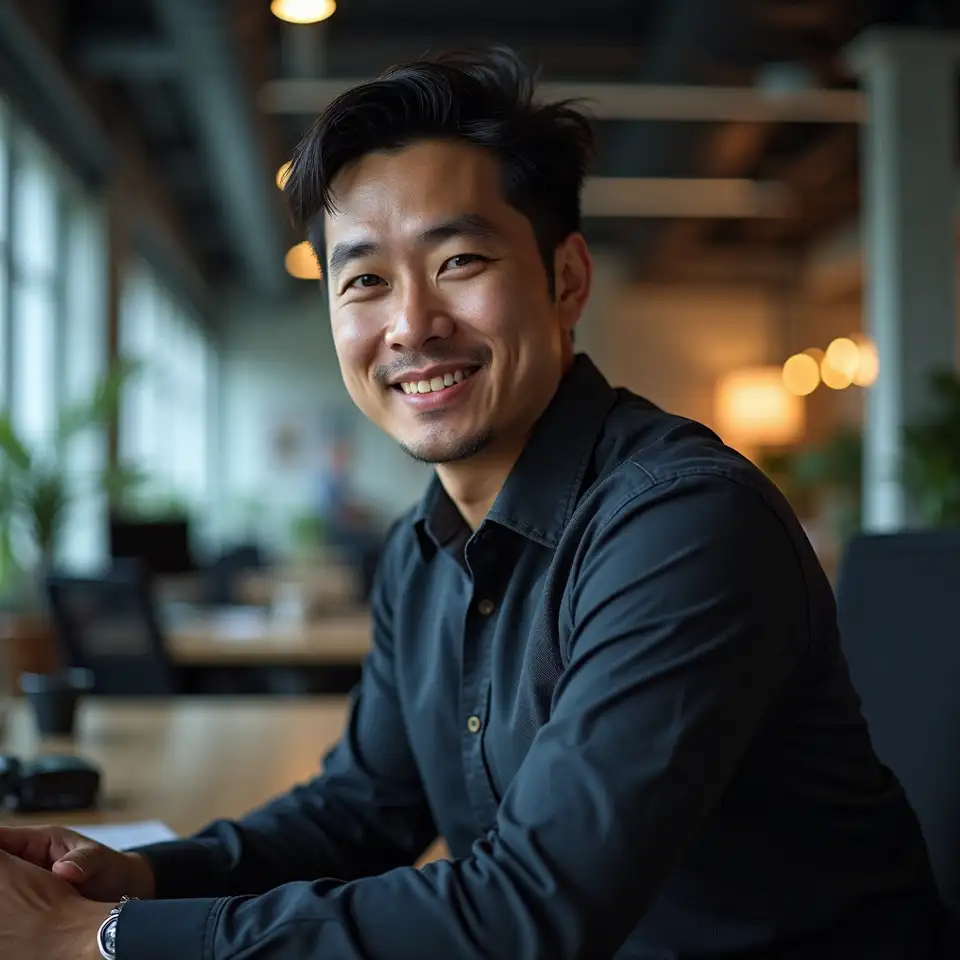
Marcus Oduya-Reyes
Senior Quantitative Developer
Marcus builds the simulation engines and stress-testing modules. His background spans academic postdoctoral work and sell-side derivatives structuring.
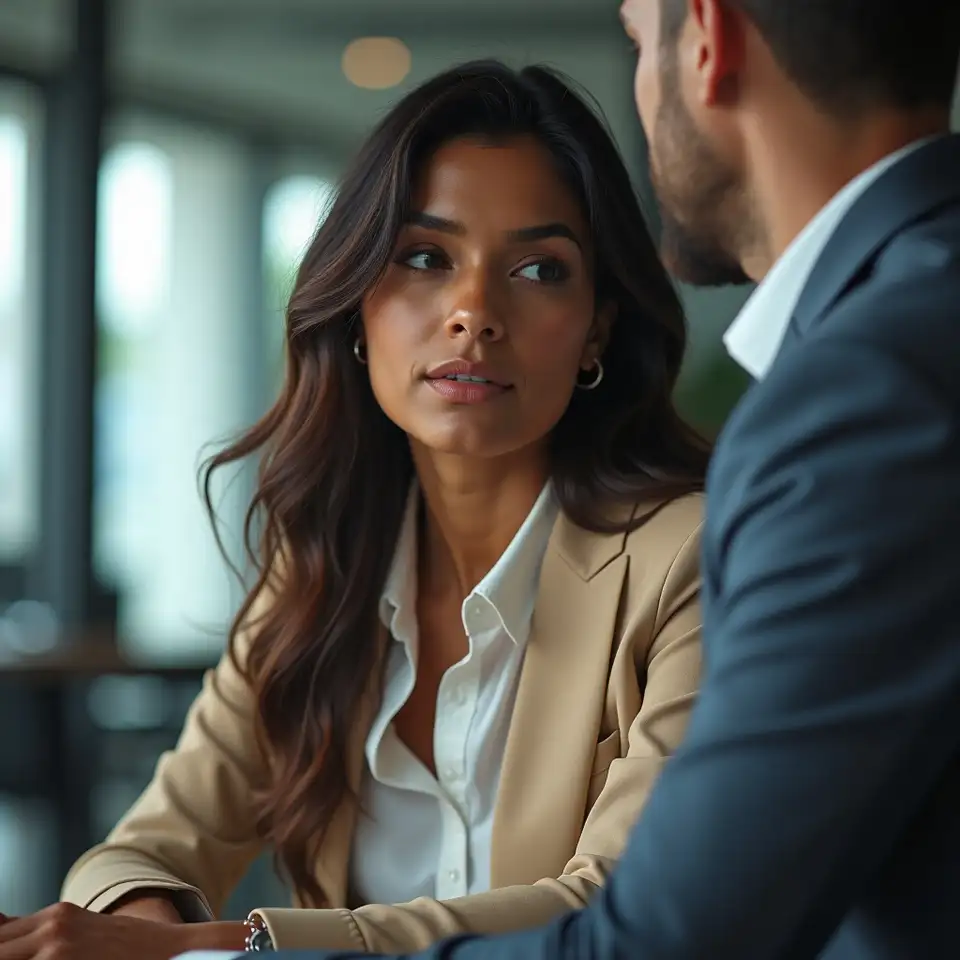
Aisha Patel-Nkosi
Client Analytics Lead
Aisha runs the diagnostic process that maps client portfolios to our model parameters. She previously managed currency hedging for a multinational corporate treasury.
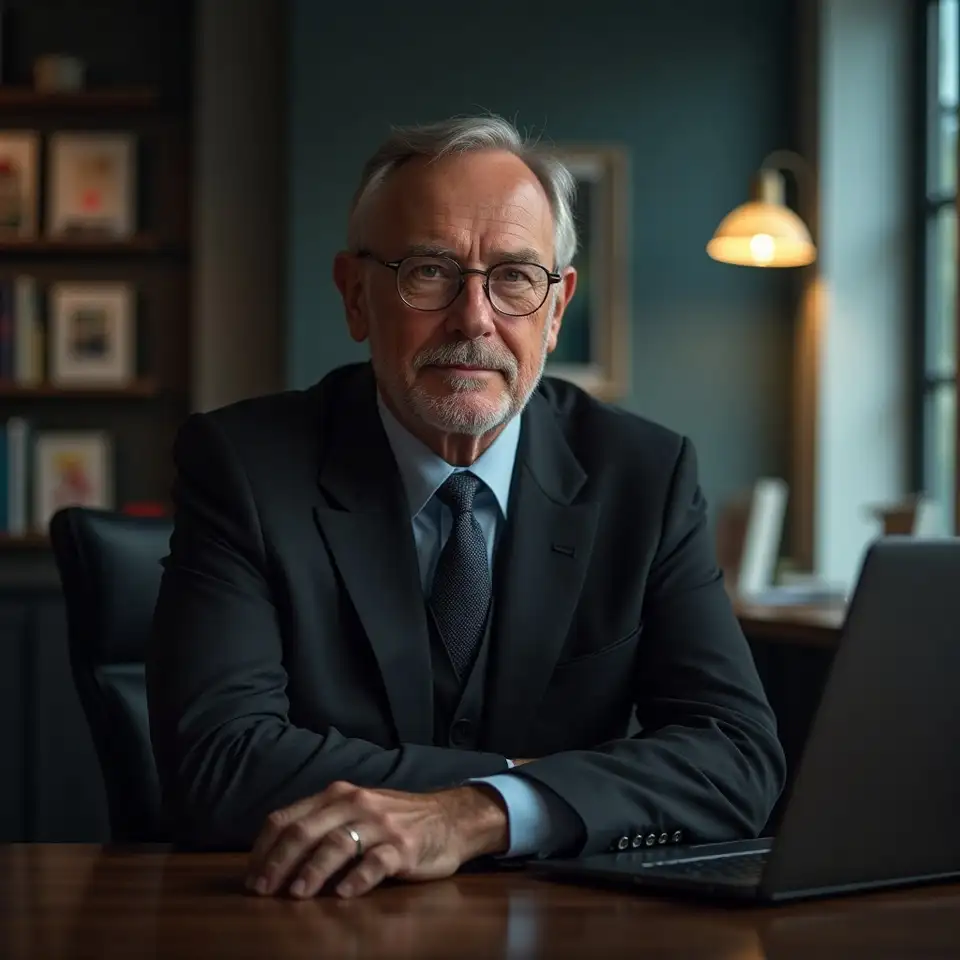
Henrik Jorgensen-Dubois
Research Director
Henrik sets the research agenda and oversees publication of working papers. He holds a visiting position at a university finance department.
What governs our work
Our mission
We equip practitioners with transparent, adaptable frameworks for multiperiod currency hedging decisions. No opaque models. No vendor lock-in. Just rigorous tools you can inspect, modify, and defend to any stakeholder.
Our vision
Within three years, every institutional allocator managing cross-border exposure will have access to hedge ratio frameworks as sophisticated as their equity or fixed income models. We are building that standard.
Intellectual rigor
Every model we publish survives internal peer review, external simulation challenges, and real portfolio stress tests. We do not ship frameworks we cannot explain.
Practical relevance
A model that ignores transaction costs, basis risk, or governance constraints is not useful. We design for the portfolio you actually manage, not the one in a textbook.
Ethical transparency
We disclose assumptions, limitations, and conflicts openly. Our clients know what the models do, what they cannot do, and how we are compensated.
Continuous improvement
Markets evolve. So do our frameworks. We publish update logs, deprecation notices, and migration guides when we replace older models with better ones.
Recognition for our approach
Quantitative Finance Innovation
Our multiperiod rebalancing framework was recognized for advancing practical hedge ratio calibration beyond static one-period models.
Academic Research Partnership
A leading business school cited our working papers in its curriculum on currency risk management for graduate finance students.
Practitioner Choice Award
Corporate treasury professionals selected our diagnostic methodology as the most implementable approach in a 2025 industry survey.
Open Science in Finance
We received acknowledgment for publishing full model documentation and replication code alongside every framework release.